













US Stock Market Today: Wall Street Steadies After a Brutal Week as Futures Point Higher Ahead of CPI
US stocks steadied on Monday, 9 November 2026, after one of the most volatile weeks of the year. Friday brought a partial rebound in technology shares — the Nasdaq rose 1.1% and the S&P 500 added 0.32% — but the week still ended deep in the red, with the Nasdaq down 3.37% and in correction territory. Strong October jobs data has pushed up the odds of a Federal Reserve rate hike in December, while Nvidia fell in premarket trading on unverified reports about its chief executive and Berkshire Hathaway's cash pile hit a record $377.4 billion. Investors now wait for Tuesday's inflation report.
US Stock Market Today: Wall Street Steadies After a Brutal Week as Futures Point Higher Ahead of CPI
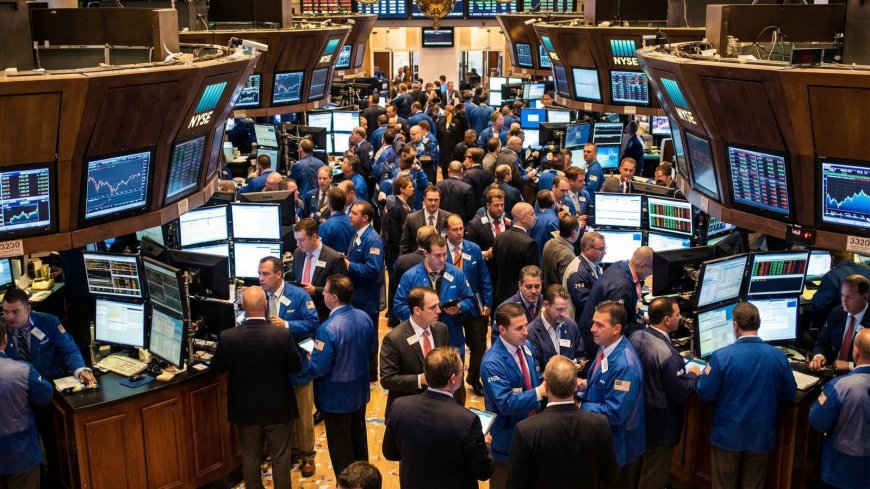
US stock index futures pointed higher on Monday, 9 November 2026, as Wall Street tried to steady itself after one of the most volatile weeks of the year. Friday brought a partial recovery in technology shares, but it did not repair the damage: the Nasdaq still finished the week down 3.37% and has now fallen into correction territory, more than 10% below its peak from a month ago. The market starts the new week balancing a rebound in AI equities against sharply higher expectations of a Federal Reserve rate hike in December, with Tuesday's inflation report firmly at the centre of the calendar.
Friday's rebound: tech bounces back, but the week still ended in the red
Technology stocks staged a broad rebound on Friday after their sharpest setback in more than a year. The S&P 500 gained 0.32% to 7,376.86 and the Nasdaq Composite rose 1.1% to 24,579.43, while the Dow Jones slipped 0.46% to 51,285.73. Dip buyers returned to chipmakers a day after the Nasdaq 100 recorded its worst session since March 2020: the Nasdaq 100 rose 1.35% and the Philadelphia Semiconductor Index gained 4.2%, lifting the S&P 500 even as most of its constituents closed lower.
The bounce did not repair the damage from the week. The Nasdaq lost 3.37%, the S&P 500 fell 2.68% — its largest weekly percentage decline since the week ended 4 April 2025 — and the Dow declined 0.94%. Thursday's selloff was the trigger: the Nasdaq fell 5.5% and the S&P 500 dropped 4.4% in a single session, wiping out about $2.3 trillion in value, driven by speculation that the Democrats' sweep of Congress in the midterm elections will bring restrictions on AI and the data-centre buildout that supports it.
Strong jobs data pushes December rate-hike bets higher
Friday's US employment report shifted the rate outlook. Nonfarm payrolls increased by 165,000 in October, more than twice economists' expectations of roughly 60,000, while the unemployment rate fell to 4.1%. Consumer sentiment also rose to a three-month high in early November. Money markets responded by lifting the odds of a Federal Reserve hike in December to around 78%. Fed speakers Bowman, Goolsbee and Barkin are all scheduled to speak on Monday, and the October Consumer Price Index report follows on Tuesday — the week's biggest scheduled test for markets.
Futures point higher as Asia rebounds
US futures were firmer on Monday morning after Friday's technology rebound, with Asian equities also recovering. S&P 500 futures were up 0.47%, Nasdaq 100 futures up 0.33%, Dow futures up 0.71% and Russell 2000 futures up 0.78%. The picture was mixed through the morning, with some readings showing Nasdaq futures slightly lower, but the broad direction was positive. In Asia, the MSCI Asia Pacific index rose about 2.3%, its biggest jump since July, led by Taiwan's TSMC. Europe was heading for a mostly negative open, with the FTSE 100 slightly higher while the DAX and CAC 40 pointed lower.
Nvidia falls on unverified reports; Berkshire's cash hits a record
Nvidia shares fell more than 4% in premarket trading following reports containing allegations about chief executive Jensen Huang and a possible independent investigation by the company's board. The allegations and the reported board investigation have not been independently verified. Berkshire Hathaway reported third-quarter operating earnings of $12.7 billion, a decline of 5.8% from $13.48 billion a year earlier, while its cash reserves increased to a record $377.4 billion during the quarter.
What to watch this week
The week's agenda is crowded. Tuesday brings the October US Consumer Price Index report, financial results from several technology companies are due, and discussions in Washington concerning potential new regulations for artificial intelligence and data-centre development continue. The G7 meeting and US Treasury supply are also on the calendar. For now, the market is balancing strong AI-related earnings against labour data and the prospect of tighter policy — and Tuesday's inflation numbers will show which side of that balance is winning.
Sources
- Saxo Bank — November 9 2026 morning briefing
- The Rivkin Report — Morning Market Wrap, 9 November 2026
- ADVFN — US Futures Mixed Ahead of Inflation Report, 9 November 2026
- NordFX — Market Pulse, November 9, 2026
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0