
















Honeywell Raises 2026 Outlook as Automation Earnings Strengthen
Honeywell Technologies raised its 2026 earnings and sales outlook after third-quarter adjusted EPS climbed 34%, giving investors a fresh industrial-sector catalyst before the October 22 U.S. open.

Honeywell Raises 2026 Outlook as Automation Earnings Strengthen
Honeywell Technologies raised its full-year sales and adjusted earnings forecasts on October 22 after stronger automation demand and improved profitability lifted third-quarter results. The release gives investors in Nasdaq-listed HON a fresh company-specific catalyst ahead of Thursday’s regular U.S. trading session.
The company reported adjusted earnings of $2.27 a share, up 34% from a year earlier, on sales of $4.994 billion. Revenue rose 1% on a reported basis and 7% organically, a measure that excludes certain currency and portfolio effects. These are quarterly business results, not a report of Thursday’s stock-market close.
A stronger outlook for the standalone automation business
Honeywell now expects 2026 adjusted earnings of $8.40 to $8.45 a share, compared with its previous $8.05 to $8.35 range. Sales guidance increased to $20.0 billion–$20.1 billion from $19.8 billion–$20.0 billion, while expected organic growth moved to 4%–5% from 3%–4%.
Management described the results as its first quarter as a standalone company. For shareholders, the report offers an early look at how the reshaped automation portfolio is performing, rather than relying on comparisons with the former group’s broader business mix.
Backlog grew 7% to nearly $19 billion, excluding the Warehouse and Workflow Solutions and Productivity Solutions and Services divestitures. Operating income rose 79% to $740 million, and operating margin reached 14.8%.
Why reported earnings fell while adjusted earnings rose
Reported earnings per share declined 20% to $2.40. That decline does not tell the same story as the adjusted result: the prior-year period included a one-time gain from the Resideo termination agreement. Investors should therefore keep the reported and adjusted measures separate rather than treating either as interchangeable.
The distinction also matters for cash flow. Operating cash flow fell 74% to $607 million against a prior-year period boosted by that settlement. Honeywell’s adjusted free cash flow, a non-GAAP measure with additional exclusions, rose 15% to $688 million. The company raised its full-year free-cash-flow expectation to approximately $2.1 billion.
Growth across three segments, with uneven margins
Building Automation and Process Automation and Technology each delivered 8% organic sales growth. Industrial Automation grew 4% organically, although its reported sales fell 23% following portfolio changes. Process Automation’s segment margin declined as project mix and an acquisition weighed on profitability, showing that the improvement was not uniform across the business.
Honeywell scheduled its investor call for 8:30 a.m. Eastern time on October 22. The central question for investors is whether order growth and cost reductions can sustain the upgraded outlook despite inflation, trade-policy uncertainty and changes in industrial demand. The guidance remains a management forecast, not a guarantee.
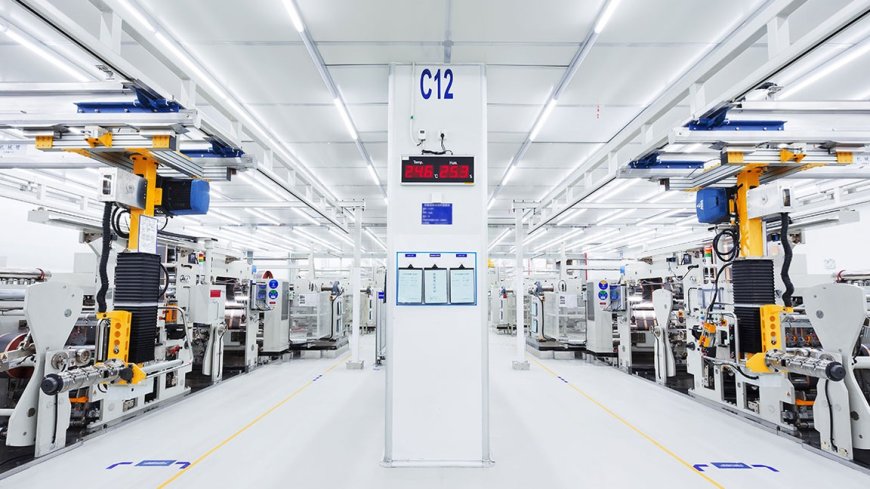
Main image: illustrative factory automation photograph by Homa Appliances / Unsplash, cropped to 16:9 under the Unsplash License. It does not depict a Honeywell facility.
Sources
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0